
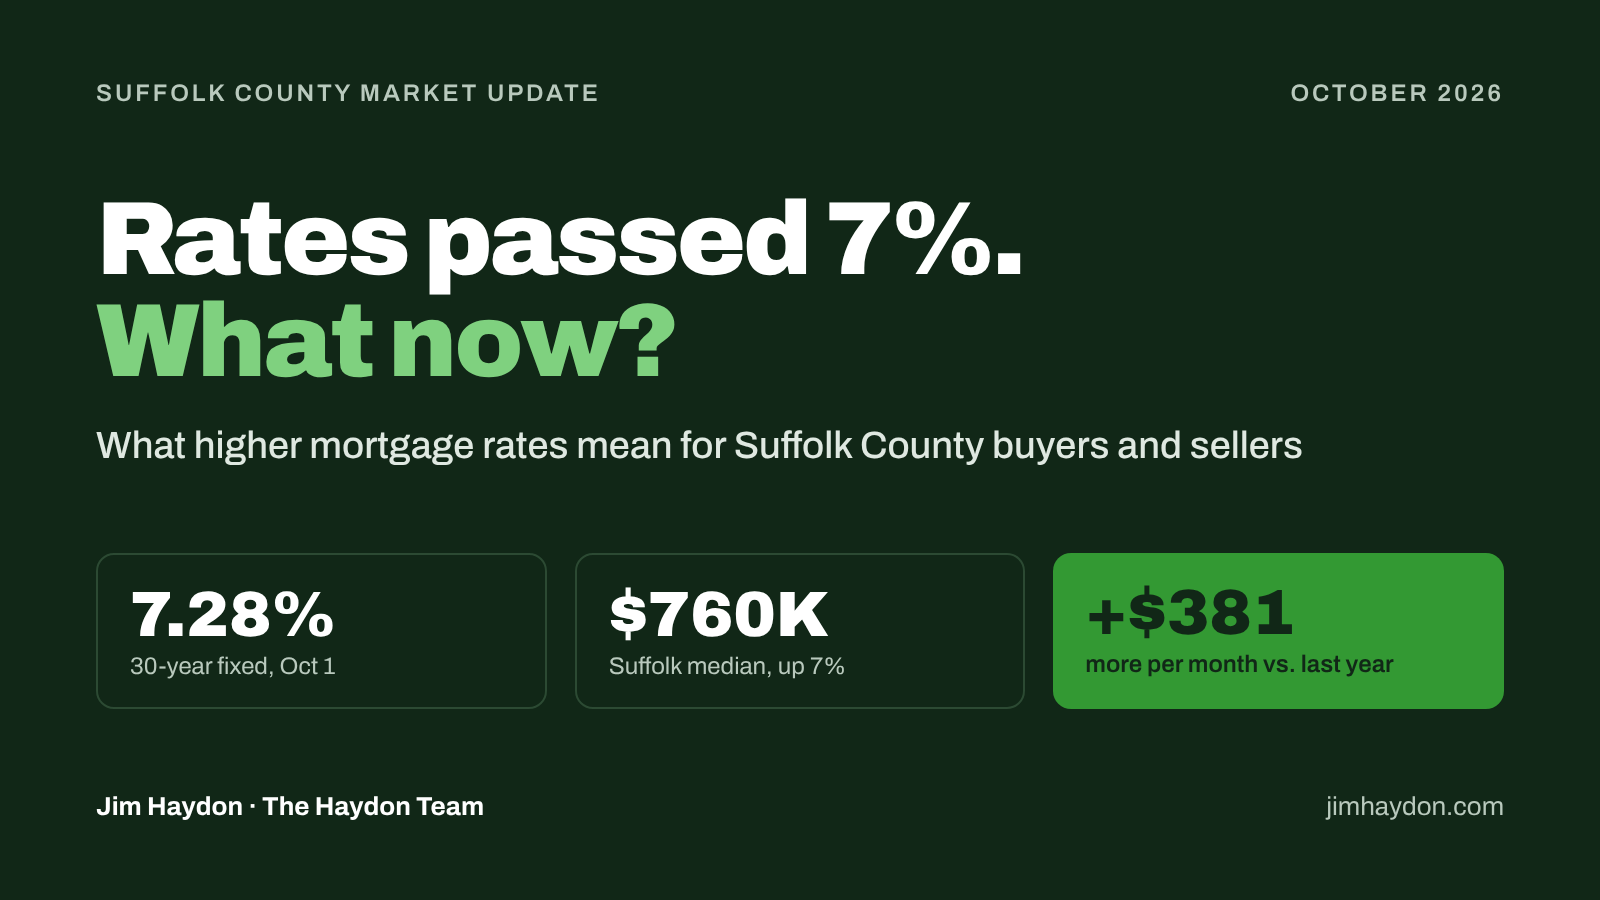
Quick Answer: The average 30-year mortgage rate hit 7.28% on October 1, 2026, the highest since late 2023. That adds about $380 a month to the payment on a median-priced Suffolk County home. But prices haven't dropped. Suffolk's median single-family sale price reached $760,000 in August, up 7% from a year ago. Buyers are paying more each month, and sellers still hold the edge if they price right.
If you've been watching the news, you've probably seen the headlines. The Fed raised rates. Mortgage rates jumped past 7%.
So what does that actually mean for you, here in Smithtown, Commack, Kings Park, or anywhere in Suffolk County?
I've been selling homes on Long Island for 14 years. I've seen rates go up and down more than once. Here's what I'm telling my buyers and sellers right now, in plain English.
Why did mortgage rates go up in October 2026?
Mortgage rates went up because inflation is running hot and the Federal Reserve raised its benchmark rate.
On September 16, 2026, the Fed raised its key rate by a quarter point. The new range is 3.75% to 4%. It was the first increase since 2023.
Higher oil and energy prices pushed inflation back up this year. The Fed is trying to cool it down. Most Fed officials also expect one more hike before the end of the year.
Here's the part most people miss. The Fed doesn't set mortgage rates directly. Mortgage rates follow the 10-year Treasury yield, which moves with inflation fears.
When the market expects higher rates for longer, mortgage rates climb fast. That's exactly what happened. Freddie Mac's weekly average went from 7.03% to 7.28% in just one week.
How much more will I pay each month at 7% rates?
On a median-priced Suffolk home, a 7.28% rate costs about $380 more per month than last year's rate.
Let's use real numbers. Say you buy a $760,000 home, the Suffolk median, with 20% down. Your loan is $608,000.
- At 6.34% (last year's rate): about $3,779 a month in principal and interest
- At 7.28% (today's rate): about $4,160 a month
That's roughly $381 more each month, or about $4,570 a year. Taxes and insurance come on top of that.
Now compare it to buying the same kind of home a year ago. Last August, the Suffolk median was $710,000. At 6.34%, that payment was about $3,531.
Today's buyer is paying about $630 more per month for the typical home. Higher prices and higher rates both added to the bill.
There's a second way to look at it. A buyer whose budget was $3,779 a month last year could afford about $760,000. At today's rate, the same payment buys about $690,000.
That's roughly $70,000 less house for the same monthly budget.
Should I wait for mortgage rates to come down before buying?
Waiting is a gamble right now, because the Fed is signaling more hikes, not cuts.
Earlier this year, rates were under 6% at one point. A lot of buyers waited for them to drop even further. Instead, they went the other way.
Prices haven't waited either. Suffolk's 12-month median rose almost 6% over the past year. If that pace continues, waiting could cost you on price even if rates ease.
Here's how I explain it at the kitchen table. You can refinance a rate later if rates fall. You can't go back and buy at last year's price.
That doesn't mean everyone should rush. It means you should run your own numbers, not the headlines.
A few things worth asking your lender about:
- FHA loans. FHA rates were pricing near 6% in early October, well below conventional rates.
- ARMs. A 5- or 7-year adjustable rate can lower your starting payment if you plan to move or refinance.
- Seller-paid buydowns. More sellers are willing to help with your rate instead of cutting the price.
There's also a quiet upside. When rates jump, some buyers step back. That can mean fewer bidding wars and more room to negotiate.
Will Suffolk County home prices drop because of higher rates?
Not likely in the short term, because there still aren't enough homes for sale.
Prices drop when sellers outnumber buyers. That isn't happening in Suffolk.
In August, Suffolk had 3,129 single-family homes for sale, down almost 4% from a year earlier. New listings were up about 3%, but buyers snapped them up fast.
The market had about 3.3 months of supply, according to NYSAR. A balanced market usually has 5 to 6 months. We're well short of that.
Homes are still moving, too. The typical Suffolk home sold in 39 days in August. Sellers got about 102% of their original asking price.
What higher rates usually do is slow the pace, not crash prices. Expect fewer multiple-offer weekends. Expect buyers to be a little pickier. But a well-priced home in Smithtown or Saint James should still sell.
Is now a good time to sell my house in Suffolk County?
Yes, for most sellers, but pricing matters more than it did six months ago.
You still have a lot going for you. Inventory is low. Prices are near record highs. Homes are selling above asking on average.
But the buyer pool has changed. Every buyer's budget just got smaller. Someone who was approved at $760,000 in the spring may top out closer to $690,000 now.
That means overpricing is riskier. A home priced above the market will sit, and a home that sits starts to look like a problem.
Here's what I'm recommending to sellers right now:
- Price it right from day one. Your first two weeks bring in the most buyers.
- Think about a rate buydown credit. It can lower a buyer's payment more than the same dollars off the price. It also protects your sale price for the neighborhood comps.
- Don't wait for spring. Fall listings face less competition. Spring usually brings more sellers onto the market.
What should move-up buyers do if they need to sell and buy?
Move-up buyers are often in the best spot right now, because they sell high and buy in the same market.
If you're in a starter home in Lake Grove or Nesconset, your equity has likely grown a lot. That cash can lower the loan you need on your next home.
A bigger down payment means a smaller loan. A smaller loan means the higher rate stings less.
The tricky part is timing. Selling first is safer, but you may need a short-term rental or a rent-back from your buyer. Buying first can mean carrying two payments for a while.
The right answer depends on your equity, your income, and your nerves. This is a plan worth sketching out before you list.
Local Market Snapshot
Measure | Latest figure | Source |
|---|---|---|
30-year fixed rate (week of Oct 1, 2026) | 7.28% (year ago: 6.34%) | Freddie Mac PMMS |
15-year fixed rate (week of Oct 1, 2026) | 6.60% | Freddie Mac PMMS |
Fed funds target (Sept 16, 2026) | 3.75%–4.00% | Federal Reserve |
Suffolk median single-family sale price (Aug 2026) | $760,000, up 7.0% year over year | OneKey MLS |
Suffolk single-family homes for sale (Aug 2026) | 3,129, down 3.9% | OneKey MLS |
Suffolk median days on market (Aug 2026) | 39 days | OneKey MLS |
Share of original list price received (Aug 2026) | 102.2% | OneKey MLS |
Suffolk months of supply (Aug 2026) | 3.3 months | NYSAR |
By the Numbers
- 7.28% — Freddie Mac's 30-year average on October 1, the highest since November 2023
- $760,000 — Suffolk's median single-family sale price in August 2026
- +7.0% — how much that median rose from August 2025
- ~$381/month — extra principal and interest on a $608,000 loan at 7.28% vs. 6.34%
- ~$70,000 — how much less home the same monthly budget buys at today's rate
- 3.3 months — Suffolk's housing supply, about half of a balanced market
- 39 days — typical time for a Suffolk home to sell in August
- 1,119 — Suffolk single-family closings in August, almost flat from a year ago
Frequently Asked Questions
What is the average mortgage rate on Long Island right now? Long Island rates track national averages closely. Freddie Mac's 30-year average was 7.28% on October 1, 2026. Your own rate depends on credit, down payment, and loan type.
Will mortgage rates go down in 2026? Most Fed officials expect one more rate hike this year, not a cut. Mortgage rates could still dip if inflation cools, but nobody can promise it.
Are Suffolk County home prices going down? No. The August median was $760,000, up 7% from a year ago. Low inventory is keeping prices firm even as rates rise.
Is it smart to buy now and refinance later? It can be, if the payment works for your budget today. Refinancing has closing costs, so plan on today's payment being your payment until rates truly drop.
What is a rate buydown? A buydown is money paid upfront to lower your mortgage rate. A seller can offer it as a credit, which often helps a buyer more than a price cut.
Should I sell my house before rates go higher? If you're already planning to move, fall is a solid window. Inventory is tight, and buyers who are shopping now are serious.
Bottom Line
Higher rates change the math, but they don't change the market overnight.
Buyers, focus on the monthly payment you're comfortable with. Look at FHA, ARMs, and seller credits before you decide to wait.
Sellers, you still have tight inventory and strong prices on your side. Just price for today's buyer, not last spring's buyer.
Every town in Suffolk is a little different. What's true in Commack may not be true in Head of the Harbor.
Curious what your home is worth in today's market? Get a free home value report or contact Jim Haydon at https://jimhaydon.com.
Check out this article next